
Insurance companies evaluate personal injury claims by reviewing the circumstances of an accident, determining whether a covered party may be legally responsible, examining medical evidence, and estimating recoverable damages. The process may involve accident reports, witness statements, medical records, photographs, financial documentation, and applicable insurance policy terms.
In New York, the evaluation process also depends on the type of claim. A car accident may involve no-fault benefits and a separate bodily injury liability claim. A slip-and-fall accident may require proof that a property operator created or had notice of a dangerous condition. Workplace accidents, medical malpractice claims, and other injuries can involve additional legal requirements.
An insurance company’s settlement offer is not automatically the same as the full value of a legally supportable claim. Insurers may dispute liability, medical causation, treatment costs, permanent injuries, or future damages. Understanding how those issues are assessed can help injured people evaluate offers and respond to claim-related questions using reliable evidence.
Quick Answer
How do insurance companies evaluate personal injury claims after an accident?
Insurance companies generally evaluate a personal injury claim through five major considerations:
- Coverage: Whether an applicable insurance policy covers the incident and potential liability.
- Liability: Whether the insured person or business was legally responsible for the accident.
- Medical Causation: Whether the accident caused or aggravated the injuries for which compensation is requested.
- Damages: The value of documented medical expenses, lost earnings, pain and suffering, and other recoverable losses.
- Settlement Risk: The likelihood of a different outcome through continued negotiations, litigation, or trial.
The insurer may accept liability, dispute responsibility, request additional documentation, make a settlement offer, or deny the claim.
New York also regulates certain insurer practices through Insurance Law § 2601 and 11 NYCRR Part 216. These rules do not guarantee acceptance of every claim or require an insurer to agree with the claimant’s proposed settlement amount.
Key Takeaways
- Coverage Comes First: The insurer identifies the relevant policy, insured parties, coverage provisions, exclusions, and limits.
- Liability Matters: Accident reports, photographs, witness statements, and other evidence may determine whether a covered party was negligent.
- Medical Evidence Is Essential: Insurers examine diagnoses, treatment, prior medical conditions, and whether the accident caused the claimed injuries.
- Damages Are Evaluated Separately: Medical bills alone do not establish the full value of pain and suffering or future financial losses.
- Settlement Offers Reflect Disputes: An insurer may reduce an offer because of liability uncertainty, comparative fault, causation disputes, or coverage limitations.
- No-Fault Is Different: New York no-fault benefits have separate rules and deadlines from ordinary bodily injury liability settlements.
- 2026 Auto Reforms Matter: Certain New York motor vehicle cases now have revised serious-injury and comparative fault rules.
- Releases Have Consequences: A settlement may resolve claims for future complications, making the scope of the agreement important.
What Happens When an Insurance Company Receives an Injury Claim?
A claim usually begins when an injured person, policyholder, or authorized representative notifies an insurance company about an accident.
The insurer generally opens a claim file and determines what information is needed.
Initial Claim Registration
The insurer may record:
- Date and location of the accident
- Identity of the claimant
- Identity of the insured person or business
- Type of accident
- Available policy information
- Reported injuries
- Involved vehicles or property
- Witness information
- Initial medical treatment
- Contact information
The insurer may assign a claim number and an adjuster.
Opening a claim does not establish that coverage exists or that compensation is owed.
Assignment to a Claims Adjuster
A claims adjuster investigates the reported loss and evaluates the claim under the applicable policy and legal requirements.
Depending on the claim, the adjuster may communicate with the insured person, injured claimant, medical providers, witnesses, and other relevant parties.
The adjuster may also review information prepared by investigators, medical consultants, or legal counsel.
Coverage Review
The insurer determines whether the reported incident potentially falls within the policy.
Questions may include whether the policy was active, whether the person involved qualifies as an insured, and whether a relevant exclusion applies.
Initial Investigation
The adjuster may request accident reports, photographs, witness statements, and available medical documentation.
The insurer may continue its investigation while the injured person’s treatment is ongoing.
Claim Evaluation
Once sufficient information is available, the insurer may assess liability, damages, available coverage, and settlement options.
The process is not always linear. Additional evidence may change an earlier evaluation.
What Is the Difference Between First-Party and Third-Party Insurance Claims?
Understanding which insurance claim is involved is essential because different coverage provisions and legal rules apply.
First-Party Claims
A first-party claim generally involves a person requesting benefits under an insurance policy that provides coverage to that person.
Examples may include qualifying no-fault personal injury protection benefits or certain medical payments coverage.
The issue is primarily whether the claimant qualifies for the contracted or statutory benefits.
Third-Party Liability Claims
A third-party liability claim generally involves someone seeking compensation because an insured person or business allegedly caused an injury.
For example, a customer injured by a negligently maintained store entrance may submit a claim to the business’s liability insurer.
The insurer may investigate whether its insured is legally responsible.
How Are the Claims Different?
| Factor | First-Party Claim | Third-Party Liability Claim |
| General Purpose | Obtain benefits under applicable coverage | Recover damages for another party’s legal responsibility |
| Main Question | Does the coverage apply to the claimed loss? | Did the insured cause legally compensable harm? |
| Example | New York no-fault medical benefits | Bodily injury claim against an at-fault driver |
| Common Evidence | Eligibility, treatment, qualifying expenses | Negligence, medical causation, damages |
| Payment Rules | Policy and applicable benefit regulations | Liability law, policy coverage, settlement terms |
| Disputes | Eligibility, necessity, documentation, benefit limits | Fault, injuries, valuation, insurance coverage |
The same accident may produce both types of claims.
For example, an eligible person injured in a car accident may receive no-fault benefits while separately pursuing a liability claim.
How Do Insurance Companies Determine Who Was at Fault?
Liability is often the first major dispute in a third-party injury claim.
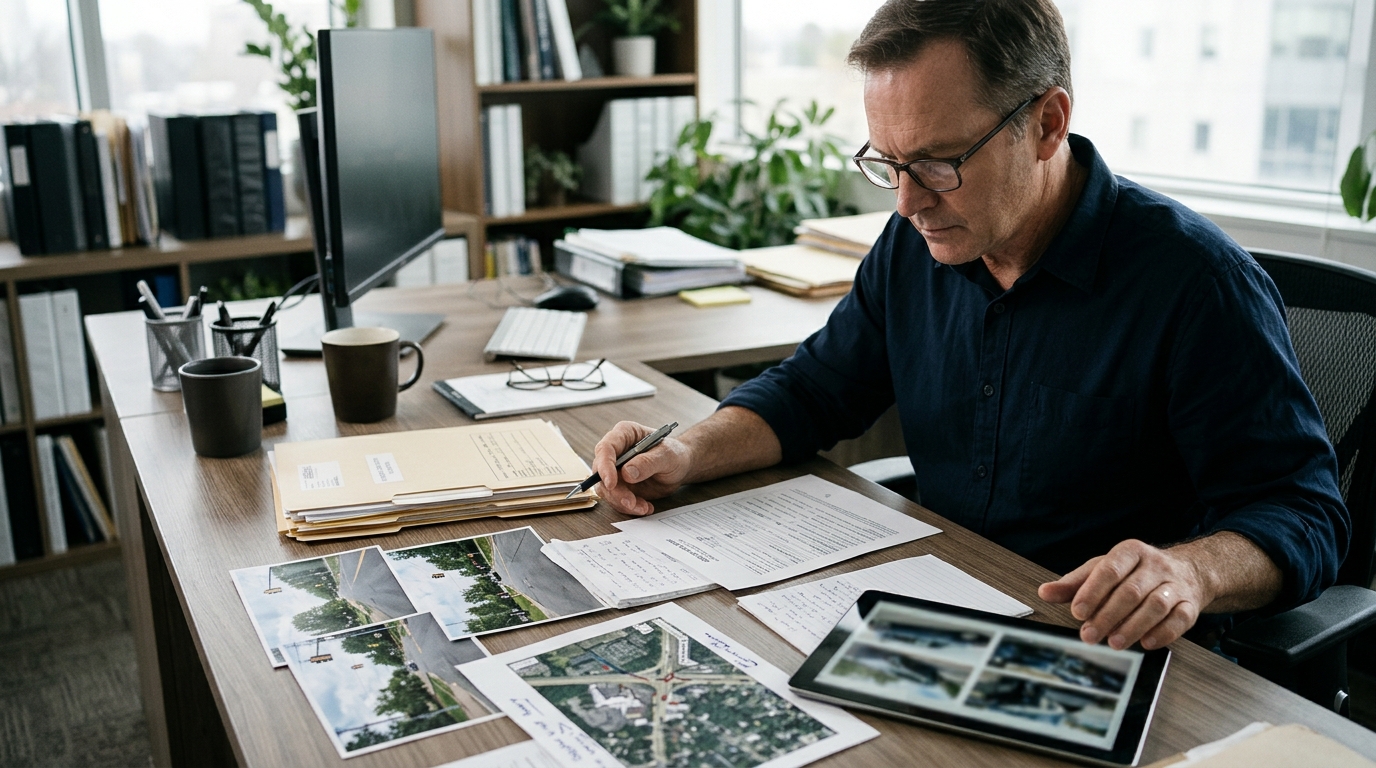
The insurer investigates whether its insured owed an applicable duty of care, breached that duty, and caused the injury.
Reviewing Accident Reports
Police and other incident reports may identify the location, involved parties, initial statements, and relevant circumstances.
However, a report does not automatically establish negligence.
For example, a police officer may prepare a crash report based on statements from people who witnessed the collision.
The report’s significance depends on the underlying information and applicable evidentiary rules.
Reviewing Photographs and Video
Photographs may show:
- Vehicle damage
- Road conditions
- Traffic signals
- Dangerous property conditions
- Damaged equipment
- Obstructions
- Accident location
- Surrounding visibility
Surveillance footage may help establish how an incident occurred.
An insurer may use video to support or challenge the claimant’s description.
Evaluating Witness Statements
Witnesses may provide independent observations.
An insurer may consider whether the witness actually saw the accident, whether the account is consistent with physical evidence, and whether other records support it.
Reviewing Applicable Safety Rules
A claim may involve traffic laws, property maintenance requirements, or other applicable standards.
A regulatory or statutory violation may become relevant to liability.
However, the insurer must also consider causation and the legal effect of the particular rule.
Considering Multiple Responsible Parties
An accident may involve several potentially responsible people or businesses.
For example, a commercial vehicle collision may involve questions concerning the driver, vehicle owner, maintenance contractor, or another motorist.
Each party’s responsibility must be evaluated independently.
How Do Insurance Companies Evaluate Liability in Different Accidents?
Different accident categories require different evidence.
An insurer should not treat every injury claim as an ordinary car accident case.
Car Accident Claims
Potential evidence includes:
- Police reports
- Vehicle damage
- Traffic camera footage
- Dashboard camera recordings
- Witness statements
- Relevant vehicle data
- Traffic rules
- Driver testimony
The investigation may focus on speeding, distracted driving, right-of-way violations, unsafe turns, or other conduct.
Slip-and-Fall Claims
A premises liability claim may require evidence that the property operator created a dangerous condition or had actual or constructive notice of it.
Potential evidence includes:
- Photographs of the hazard
- Maintenance records
- Cleaning logs
- Earlier complaints
- Surveillance footage
- Witness testimony
- Property control information
A fall occurring inside a business does not automatically establish liability.
Construction and Workplace Injuries
An insurer may examine jobsite responsibilities, contracts, equipment condition, safety procedures, and relevant statutory duties.
Workers’ compensation and separate third-party liability claims may apply differently.
Medical Malpractice Claims
Medical malpractice insurers may evaluate whether a healthcare professional departed from accepted standards of care and caused injury.
These claims may require extensive records and qualified medical opinions.
Dog Bite Claims
An insurer may investigate the dog’s prior behavior, owner knowledge, the circumstances of the attack, and whether the owner exercised reasonable care.
New York recognizes ordinary negligence and strict liability based on known vicious propensities as separate potential legal theories.
What Is Comparative Neggligence and Why Does It Affect Settlement Offers?
Comparative negligence concerns whether the injured person’s own legally attributable conduct contributed to the accident.
An insurer may consider comparative fault when evaluating potential recovery.
New York’s General Rule
Under CPLR § 1411(a), ordinary negligence claims generally follow a proportional reduction framework.
For example, a claimant found 25% responsible for an accident may generally have recoverable damages reduced by 25%.
Illustrative Settlement Evaluation
| Factor | Illustrative Amount |
| Total Legally Established Damages | $100,000 |
| Claimant’s Share of Fault | 25% |
| Fault-Based Reduction | $25,000 |
| Remaining Damages | $75,000 |
This illustration assumes the general comparative negligence rule applies.
It is not an estimate of what an insurer should offer in a particular case.
What Changed in May 2026?
New York introduced CPLR § 1411(b), effective May 26, 2026, for certain motor vehicle personal injury actions subject to Insurance Law Article 51.
In covered actions, recovery is barred when the claimant’s legally attributable fault exceeds that of the defendant or the combined fault of the defendants against whom recovery is sought.
This differs from the general rule applicable to many other negligence claims.
Why Does the Distinction Matter?
An insurer evaluating a covered motor vehicle injury action may consider whether the claimant’s percentage of fault could prevent recovery altogether.
However, the same rule should not automatically be applied to an ordinary slip-and-fall, medical malpractice, or unrelated third-party workplace claim.
The New York CPLR § 1411 establishes the applicable comparative fault provisions.
How Do Insurers Determine Whether an Accident Caused an Injury?
Medical causation is often a major part of claim evaluation.
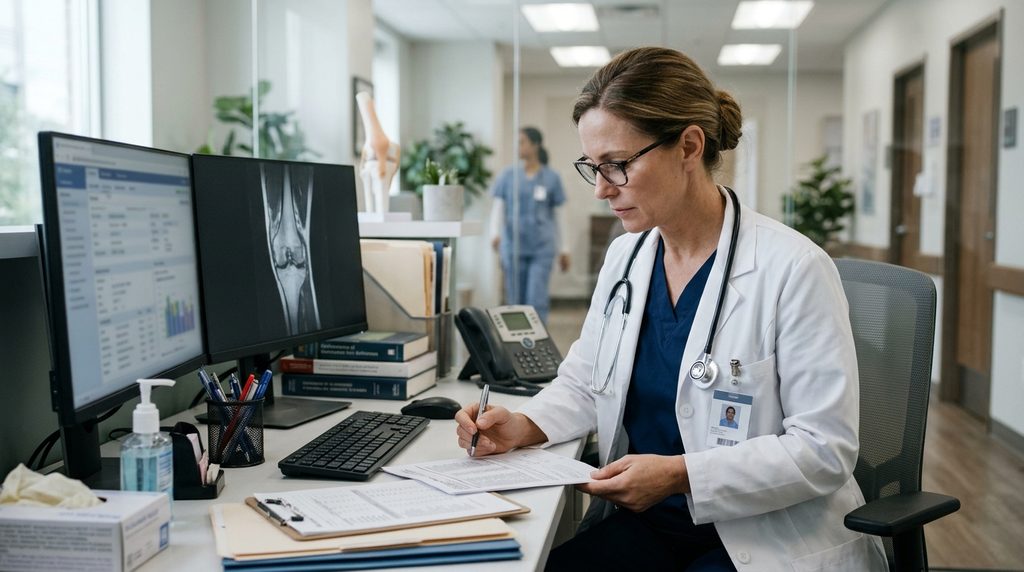
The insurer may accept that an accident happened but dispute whether it caused every diagnosed condition.
Reviewing Initial Medical Records
Emergency treatment records may identify symptoms and medical findings documented shortly after the incident.
The insurer may examine whether the claimant sought treatment promptly and which injuries were initially identified.
Reviewing Diagnostic Testing
X-rays, MRI reports, and CT scans may provide objective medical findings.
However, an abnormal imaging result does not automatically establish that the accident caused the condition.
Medical interpretation may be necessary.
Evaluating Preexisting Conditions
The insurer may review relevant earlier medical history.
For example, the claimant may have undergone treatment for the same body part before the accident.
A preexisting condition does not automatically eliminate a claim.
The relevant issue may be whether the accident caused a new injury or aggravated an existing one.
Evaluating Treatment Gaps
A gap in treatment may raise questions about the severity or cause of an injury.
However, an interruption does not automatically invalidate a claim.
Possible explanations include completion of treatment, medical advice, insurance difficulties, or other circumstances.
Reviewing Medical Opinions
Some claims require specialist opinions concerning whether a condition is related to the accident.
The insurer may obtain a medical review or other evaluation permitted under the applicable policy and law.
Why Does Causation Affect the Offer?
If the insurer concludes that only part of the medical treatment was related to the accident, it may dispute the remaining expenses and damages.
The claimant may need additional evidence addressing the disagreement.
How Do Insurance Companies Evaluate Medical Expenses?
Medical expenses are commonly part of the economic damages analysis.
However, an insurer may review more than the total amount billed.
Emergency Medical Costs
Records may include ambulance services, emergency treatment, diagnostic testing, and hospitalization.
Specialist Treatment
The insurer may consider the necessity and relationship of specialist visits to the accident.
Surgery and Procedures
Surgical records may establish the nature of the treatment and the underlying medical condition.
Rehabilitation
Physical or occupational therapy records may show the duration and progress of rehabilitation.
Medication Costs
Prescriptions and related expenses may be included when appropriate.
Future Medical Expenses
Future care may require medical opinions establishing the likely need for treatment.
The insurer may question costs based on speculative or unsupported treatment plans.
Why Might the Insurer Dispute a Medical Bill?
Potential reasons include:
- Coverage limitations
- Questions about medical necessity
- Disagreement about accident causation
- Duplicate billing
- Treatment unrelated to the injury
- Disputes concerning reasonable charges
- Incomplete records
- Applicable no-fault fee schedules
The relevant objection should be evaluated rather than assuming every disputed bill is valid or invalid.
How Are Lost Wages and Reduced Earning Capacity Evaluated?
An injury may prevent a person from working temporarily or permanently.
Insurers may examine the extent of the limitation and whether the claimed income loss is supported.
Lost Earnings
Evidence may include:
- Employer wage statements
- Pay stubs
- Tax records
- Work restriction notes
- Employment schedules
- Disability documentation
- Self-employment records
The insurer may evaluate how much work the claimant actually missed because of the injury.
Reduced Working Hours
An injured person may return to work on a reduced schedule.
The resulting income difference may be relevant when properly documented.
Self-Employment Income
Self-employed people may need business records, tax documents, invoices, and other financial information.
The analysis can be more complicated when earnings fluctuate.
Future Earning Capacity
A permanent limitation may affect the person’s ability to perform previous work or earn comparable income.
Medical, vocational, and financial evidence may be required.
Does Missing Work Automatically Establish a Wage Claim?
No.
The lost income generally must be connected to the medically supported consequences of the accident.
A claimant may need evidence showing both the limitation and the financial loss.
How Do Insurers Evaluate Pain and Suffering?
Pain and suffering is a form of noneconomic damages.
It can involve physical discomfort, emotional consequences, and other legally recognized effects of an injury.
What Factors May Be Considered?
Relevant circumstances include:
- Injury severity
- Duration of symptoms
- Type of treatment
- Surgery
- Physical limitations
- Permanent disability
- Disfigurement
- Long-term prognosis
- Interference with daily activities
- Medically supported psychological effects
The significance of each factor depends on the claim.
Is There a Standard Formula?
No.
New York does not establish one universal payment schedule for pain and suffering across ordinary personal injury cases.
Insurers may use internal methods and review past claims, but those methods do not automatically determine legally recoverable damages.
Does Every Injury Qualify for Pain and Suffering?
Not necessarily.
Some motor vehicle cases are subject to New York’s serious-injury threshold.
Other claims may involve separate legal requirements.
Can Emotional Distress Be Included?
Potentially.
The availability of emotional distress damages depends on the legal claim and supporting evidence.
Not every upsetting accident supports a separate emotional distress recovery.
How Are Permanent Injuries Valued?
Permanent impairment may require medical opinions concerning long-term limitations.
A diagnosis alone does not necessarily establish permanence or determine compensation.
How Does New York’s Serious-Injury Threshold Affect Car Accident Evaluations?
New York’s no-fault system limits certain lawsuits for noneconomic damages in covered motor vehicle cases.
To pursue pain and suffering damages under the applicable statutory framework, the claimant generally must establish a serious injury as defined by Insurance Law § 5102(d).
What Qualifies as a Serious Injury?
The current statutory categories include:
- Death
- Dismemberment
- Significant disfigurement
- A fracture
- Loss of a fetus
- Permanent loss of use of a body organ, member, function, or system
- Permanent consequential limitation of use of a body organ or member
- Significant limitation of use of a body function or system
Different categories require different proof.
What Changed in 2026?
Effective May 26, 2026, New York removed the former 90/180-day nonpermanent injury category from Insurance Law § 5102(d) for actions and proceedings commenced on or after that date.
This category previously concerned certain injuries preventing a person from performing substantially all customary daily activities for at least 90 of the first 180 days following an accident.
An insurer evaluating a newly commenced covered action should account for the applicable revised statute.
Does Every Fracture Guarantee a Settlement?
No.
A qualifying fracture may satisfy a serious-injury category, but liability, causation, and damages still must be established.
Are There Other New Motor Vehicle Restrictions?
Yes.
The 2026 reforms also introduced a $100,000 cap on noneconomic damages in narrowly defined cases involving certain at-fault drivers who operated uninsured vehicles, were convicted of specified impaired-driving conduct, or were convicted of specified felony-related conduct.
The statutory requirements and exceptions matter.
This is not a general cap on all New York car accident settlements.
The New York Department of Financial Services’ 2026 motor vehicle insurance reform guidance explains these changes.
How Does New York No-Fault Insurance Evaluate Medical and Wage Claims?
No-fault benefits follow a different process from a third-party liability settlement.
An eligible injured person may receive qualifying benefits without first proving that another driver was negligent.
What Does Standard Basic No-Fault Coverage Include?
New York’s standard basic no-fault protection generally provides up to $50,000 per eligible person for combined covered economic losses.
Benefits may include:
- Necessary medical treatment
- Qualifying rehabilitation expenses
- Partial lost earnings
- Certain additional necessary expenses
Payment remains subject to applicable statutory and regulatory limits.
What Are the Lost Earnings Limits?
Basic no-fault benefits generally provide 80% of qualifying lost earnings, up to $2,000 per month for a maximum of three years, subject to applicable offsets and coverage limits.
What Is the Initial Notice Deadline?
The eligible injured person generally must provide written notice to the appropriate no-fault insurer within 30 calendar days after the accident.
Limited exceptions may apply when the person provides a clear and reasonable written explanation for late notice.
What Are the Medical Billing Deadlines?
Written proof of medical expenses generally must be submitted within 45 days after services are provided, subject to applicable exceptions.
Proof of qualifying lost earnings and certain other expenses generally must be submitted within 90 days after the loss or expense.
When Must the Insurer Pay or Deny a No-Fault Claim?
Under 11 NYCRR § 65-3.8, no-fault benefits generally become overdue if the insurer does not pay or deny the claim within 30 calendar days after receiving the required proof, including properly requested verification.
The timing is not simply 30 days from the accident.
What Happens When Benefits Are Denied?
Depending on the circumstances, available procedures may include no-fault arbitration, court proceedings, or a complaint to the Department of Financial Services.
The Department of Financial Services’ no-fault insurance FAQs explain the relevant deadlines and benefits.
What Role Do Insurance Policy Limits Play in Settlement Offers?
Liability insurance policies generally have limits on the insurer’s payment obligations.
An insurer may evaluate both the legally supportable damages and the available coverage.
What Are Bodily Injury Liability Limits?
Bodily injury liability limits identify the maximum coverage available under specified policy terms.
An automobile policy may have separate per-person and per-accident limits.
Other liability policies may use different structures.
Can an Injury Claim Be Worth More Than the Policy Limit?
Potentially, yes.
The legal amount of damages and the insurance coverage available to pay them are different concepts.
A person may suffer losses exceeding the defendant’s available insurance.
Does the Policy Limit Guarantee Payment?
No.
A policy limit is not an automatic settlement amount.
The insurer may dispute liability, causation, damages, or coverage.
Can More Than One Policy Apply?
Sometimes.
Depending on the incident, additional coverage may come from another insured party, an umbrella policy, or another applicable source.
The relevant policies must be identified.
What if Coverage Is Disputed?
The insurer may issue a coverage reservation or denial under applicable law.
A dispute concerning coverage is separate from whether the insured person was negligent.
What Is a Personal Injury Settlement Demand?
A settlement demand presents the claimant’s position regarding liability, injuries, damages, and requested compensation.
The demand may be submitted after sufficient investigation and medical documentation are available.
What Is Commonly Included?
A demand package may contain:
- Accident description
- Identity of potentially responsible parties
- Liability evidence
- Witness statements
- Relevant photographs
- Medical records
- Diagnostic findings
- Treatment history
- Medical expenses
- Wage-loss documentation
- Evidence of future medical needs
- Requested settlement amount
The supporting evidence should match the actual claims.
Is a Demand Letter the Same as Filing a Lawsuit?
No.
A demand letter is a settlement communication.
It does not automatically commence a legal action or preserve the statute of limitations.
What Happens After the Demand?
The insurer may accept, reject, request additional information, or make a counteroffer.
Negotiations may continue.
Does the Requested Amount Determine the Claim’s Value?
No.
A demand reflects the claimant’s proposed valuation.
A court, jury, or negotiated agreement may produce a different result.
Why Do Insurance Companies Make Low Settlement Offers?
An offer may be lower than the claimant expects for several reasons.
Some reasons involve genuine disputes about liability or damages.
Others may concern incomplete information or differences in valuation.
Disputed Liability
The insurer may argue that its insured was not responsible or that another party caused the accident.
Comparative Fault
The insurer may believe the injured person contributed to the incident.
Insufficient Medical Documentation
The insurer may dispute whether a diagnosis or limitation is supported by the available records.
Preexisting Conditions
An insurer may argue that part of the treatment concerns a medical condition unrelated to the accident.
Uncertain Future Treatment
If long-term medical needs have not been established, the insurer may be unwilling to include speculative costs.
Coverage Limitations
Available policy limits may restrict payment from a particular insurer.
Different Pain-and-Suffering Evaluations
The insurer and claimant may disagree about the effect of an injury on daily life.
How Can a Disputed Offer Be Evaluated?
The most useful response is generally evidence addressing the reason for disagreement.
For example, a medical causation dispute may require a qualified medical explanation.
A disputed property hazard may require surveillance footage, inspection records, or photographs.
Understanding how insurance companies handle injury claims helps distinguish an ordinary disagreement over valuation from a potential failure to follow applicable claims-handling requirements.
How Do Insurance Companies Negotiate Settlements?
Settlement negotiations involve assessing the claim’s legal strengths, damages, coverage, and the potential consequences of litigation.
Reviewing New Evidence
Additional medical records, witness statements, or expert opinions may affect the insurer’s evaluation.
Reevaluating Liability
A previously disputed accident may become clearer after reviewing video or testimony.
Reconsidering Future Losses
A claimant’s prognosis may change after surgery or additional treatment.
Appropriately supported future losses may affect the valuation.
Evaluating Litigation Risk
The insurer may consider whether the case is likely to proceed to trial and how uncertain the outcome may be.
Making Counteroffers
The parties may exchange settlement proposals.
An offer may be accepted, rejected, or followed by further negotiation.
Is There a Required Number of Offers?
No universal rule requires a fixed number of settlement offers.
The process depends on the claim and parties.
Does Every Negotiation Lead to Settlement?
No.
Some claims remain disputed and require litigation.
The possibility of settlement does not eliminate the need to comply with legal filing deadlines.
What Does New York Law Require of Insurance Companies During Claims Handling?
New York has statutory and regulatory requirements addressing unfair claims practices.
These rules apply according to their scope and should not be treated as a guarantee that an insurer must accept every demand.
New York Insurance Law § 2601
Insurance Law § 2601 prohibits unfair claim settlement practices.
The statute addresses conduct including:
- Knowingly misrepresenting material coverage facts or policy provisions
- Failing to acknowledge pertinent claim communications reasonably promptly
- Failing to adopt reasonable claim investigation standards
- Failing to attempt prompt, fair, and equitable settlement when liability is reasonably clear
- Certain other unfair claim-handling practices
The statute generally addresses conduct without just cause occurring frequently enough to constitute a general business practice.
The New York Insurance Law § 2601 provides the statutory requirements.
What Is Insurance Regulation 64?
11 NYCRR Part 216, commonly called Insurance Regulation 64, establishes requirements concerning unfair claims settlement practices and claims handling.
Its provisions address acknowledgment, investigation, settlement communications, and other matters.
How Quickly Must a Claim Be Acknowledged?
Under 11 NYCRR § 216.4, an insurer generally must acknowledge notice of a claim within 15 business days.
Separate requirements and exceptions may apply.
When Must the Insurer Identify Needed Information?
Under 11 NYCRR § 216.5, an insurer generally must inform the claimant or authorized representative within 15 business days about the forms and information reasonably believed necessary.
Does the Insurer Have to Settle Within 15 Days?
No.
The acknowledgment and information-request requirements should not be confused with a universal 15-day deadline to settle a bodily injury liability claim.
The insurer may need additional information to investigate coverage, liability, and damages.
What Happens After a Settlement Is Agreed Upon?
Under 11 NYCRR § 216.6(f), an insurer generally must pay an amount finally agreed upon in settlement within five business days after receiving the agreement or after the claimant satisfies a condition of the agreement, whichever occurs later, subject to the regulation’s requirements.
Can an Insurer Demand an Overly Broad Release?
Regulation 64 prohibits requiring a release broader than the scope of the settlement in covered claims.
The terms of a proposed release should accurately reflect the agreement.
Can Someone Sue an Insurance Company for Making a Low Offer?
Not automatically.
A low settlement offer or disagreement over claim value does not independently establish a separate cause of action against an insurer.
Does Insurance Law § 2601 Create a Private Lawsuit?
New York courts have generally held that Insurance Law § 2601 does not itself create a private cause of action for damages.
The statute provides a regulatory enforcement framework.
A person may have other legal remedies depending on the insurance contract, conduct, and circumstances.
Can an Insurance Complaint Be Filed?
Yes.
Consumers may submit appropriate complaints to the New York State Department of Financial Services concerning an insurer’s conduct.
A regulatory complaint does not automatically establish liability or compel a particular settlement amount.
The Department of Financial Services’ consumer complaint portal provides the reporting process.
Does Every Delay Constitute Bad Faith?
No.
An insurer may have legitimate reasons to investigate a claim.
The legal question depends on the specific conduct, governing duties, and available evidence.
Is a Claim Against the At-Fault Party Different?
Yes.
A personal injury lawsuit generally seeks damages from the legally responsible defendant.
A separate dispute concerning an insurer’s contractual or claims-handling obligations involves different legal considerations.
What Do New York Court Decisions Say About Insurance Settlement Conduct?
New York’s highest court has addressed the legal obligations of liability insurers when deciding whether to settle claims on behalf of their insureds.
Pavia v. State Farm Mutual Automobile Insurance Company (1993)
In Pavia v. State Farm Mutual Automobile Insurance Company, the New York Court of Appeals considered whether an insurer acted in bad faith by failing to accept a settlement demand within policy limits.
The underlying accident involved serious injuries and significant potential liability.
A settlement demand had been made, but the insurer continued investigating possible defenses before ultimately offering the policy limits.
What Standard Did the Court Establish?
The Court explained that an insurer’s failure to settle must be evaluated according to whether it demonstrated gross disregard of its insured’s interests.
That standard involves a deliberate or reckless failure to give the insured’s interests appropriate consideration.
Ordinary negligence or a mistaken judgment is not automatically enough.
What Did the Court Decide?
Although the lower courts had found bad faith, the Court of Appeals concluded that the evidence did not establish the required standard.
The insurer had continued investigating legitimate questions concerning liability.
The Court therefore rejected the bad-faith finding.
Why Does Pavia Matter?
The decision illustrates why the insurer’s investigation, available evidence, and risk to its insured are relevant to settlement decisions.
It also establishes that refusing an early demand does not automatically prove bad faith.
Smith v. General Accident Insurance Company (1998)
In Smith v. General Accident Insurance Company, the New York Court of Appeals addressed settlement conduct and the insurer’s obligations to the insured.
The decision considered whether the insurer’s conduct concerning settlement negotiations supported an excess-liability bad-faith claim.
The Court reaffirmed the gross-disregard standard.
The decision illustrates that communication about settlement opportunities and the potential exposure of the insured may become important.
What Do These Decisions Demonstrate?
These decisions establish several principles:
- Insurers May Investigate Disputed Claims: A demand does not automatically require immediate acceptance.
- The Insured’s Interests Matter: Liability insurers have obligations arising from their control of settlement and defense.
- Bad Faith Requires More Than a Low Offer: The applicable legal standard is demanding.
- Evidence at the Time Matters: Courts consider what the insurer reasonably knew during negotiations.
- A Third-Party Claimant Has Different Rights: The insurer’s duties to its policyholder should not be confused with automatic private remedies for every injured claimant.
The official Court of Appeals decision in Pavia v. State Farm explains the governing standard.
How Can Evidence Affect a Settlement Offer?
A claim’s supporting documentation may change the insurer’s evaluation.
Strong evidence can address uncertainty about liability or damages.
Accident Photographs
Photographs may show dangerous conditions, vehicle damage, or the accident location.
Surveillance Footage
Video may establish how an incident occurred.
It can support or contradict witness accounts.
Witness Statements
Independent witnesses may clarify disputed facts.
Medical Records
Medical documentation may support the diagnosis, treatment, prognosis, and medical causation.
Expert Opinions
Experts may address accident reconstruction, medical causation, future treatment, or earning capacity.
Financial Documentation
Wage records and medical bills may support economic losses.
Why Does Evidence Quality Matter?
A large number of records does not automatically establish a strong case.
The most useful evidence addresses the specific reasons liability or damages are disputed.
For example, additional photographs of unrelated parts of a store may contribute little to a dispute over how long a spill existed.
How Do Settlement Offers Differ From Jury Verdicts?
A settlement is a negotiated agreement.
A jury verdict results from a legal proceeding in which the factfinder decides the issues submitted for determination.
Settlement Considerations
Parties may settle because of:
- Liability uncertainty
- Medical causation disputes
- Litigation costs
- Time requirements
- Insurance limitations
- The desire for finality
- Risk of a different trial outcome
Trial Considerations
At trial, the parties must present admissible evidence.
A judge or jury may resolve disputed liability, fault allocation, and damages.
Are Published Settlements Reliable Valuation Tools?
Not by themselves.
Published case results may show outcomes in particular disputes, but they do not establish what another claimant should receive.
A case involving a similar diagnosis may involve different liability evidence, permanence, financial losses, or insurance coverage.
Does a High Verdict Guarantee Collection?
No.
A verdict and the amount actually collectible are different questions.
Insurance limits, responsible parties, available assets, legal defenses, and post-trial proceedings may affect recovery.
What Happens After a Personal Injury Settlement Is Accepted?
Accepting a settlement generally leads to documentation of the agreement and resolution of the covered claims.
Reviewing the Settlement Agreement
The written agreement may address:
- Settlement amount
- Parties being released
- Claims included
- Payment arrangements
- Confidentiality provisions, when applicable
- Conditions for completing the agreement
- Other negotiated terms
The scope of a release matters because it may affect later claims arising from the same incident.
Signing a Release
A release generally gives up the right to pursue specified claims covered by the settlement.
The precise language controls.
Payment
After required conditions are satisfied, the insurer generally issues payment under the agreement and applicable claims-handling requirements.
Medical Liens and Reimbursement
Some settlements involve payment obligations to healthcare programs or other parties.
These may affect the net amount the claimant receives.
Medicare Conditional Payments
Federal Medicare Secondary Payer rules permit Medicare to recover certain conditional payments when another insurer or responsible party ultimately pays for related medical expenses.
The Centers for Medicare & Medicaid Services’ recovery guidance explains the process.
Other Possible Reimbursement Issues
Depending on the claim, there may be workers’ compensation liens, qualifying medical reimbursement rights, or other obligations.
The existence and amount of a lien must be evaluated under the applicable law.
Settlement Amount Versus Net Recovery
The amount announced as a settlement may differ from the amount ultimately received after legally applicable deductions.
| Item | Illustrative Amount |
| Gross Settlement | $100,000 |
| Example Attorney Fee | $33,000 |
| Example Case Expenses | $2,000 |
| Example Valid Reimbursement Obligation | $10,000 |
| Illustrative Net Amount | $55,000 |
These figures are hypothetical and do not establish a standard fee or lien structure.
Actual deductions depend on the agreement and legal obligations.
How Long Does an Insurance Company Take to Settle an Injury Claim?
There is no universal deadline by which every New York bodily injury liability claim must settle.
The duration depends on coverage, the accident, liability disputes, medical evidence, and negotiations.
What Can Delay Evaluation?
Potential factors include:
- Disputed fault
- Multiple involved parties
- Unavailable surveillance footage
- Delayed incident reports
- Complex medical conditions
- Uncertain prognosis
- Additional surgery or treatment
- Questions about future earnings
- Insurance coverage disputes
- Pending expert evaluations
Are Minor Claims Always Faster?
Not necessarily.
A relatively limited injury may involve a serious liability dispute.
A more serious case may have clear liability but require extended medical evaluation.
Can a Claim Settle Before a Lawsuit?
Yes.
Some claims resolve through prelitigation negotiations.
Can a Claim Settle After Litigation Begins?
Yes.
Negotiations may continue during discovery, motion practice, and trial preparation.
Does Ongoing Negotiation Stop the Filing Deadline?
Not automatically.
An insurance investigation or settlement discussion does not generally suspend the statute of limitations.
What Are New York’s Personal Injury Filing Deadlines?
The deadline depends on the legal cause of action and defendant.
| Claim Type | General New York Rule |
| Ordinary Personal Injury Negligence | Generally three years under CPLR § 214(5) |
| Medical Malpractice | Generally two years and six months under CPLR § 214-a |
| Wrongful Death | Generally two years under EPTL § 5-4.1 |
| Ordinary Assault or Battery | Generally one year under CPLR § 215(3) |
| Certain Municipal Tort Claims | Notice of claim generally required within 90 days |
| Covered Municipal Negligence Lawsuits | Generally one year and 90 days |
| Claims Against New York State | Specialized Court of Claims requirements |
| Certain Claims Involving Minors | CPLR § 208 may extend the period |
Why Does the Filing Deadline Matter During Negotiations?
A claimant may be discussing settlement with an insurer while the statute of limitations continues to run.
The claimant should not assume that communication with an adjuster preserves the right to sue.
Does a Claim Number Preserve the Deadline?
No.
Opening an insurance claim does not automatically commence a civil action.
Can Different Defendants Have Different Deadlines?
Yes.
For example, a privately operated business and a public entity may be subject to different procedural requirements.
Why Are Government-Related Claims Different?
Certain municipal claims require an early notice of claim.
Claims against New York State may involve separate procedures.
The specific defendant and cause of action must be identified.
The New York Courts’ statute of limitations guidance provides general filing periods.
What Mistakes Can Weaken an Insurance Settlement Claim?
Several mistakes may reduce the quality of the evidence or complicate negotiations.
These include:
- Failing to report the accident promptly
- Missing no-fault insurance notice requirements
- Failing to preserve accident photographs
- Losing witness contact information
- Allowing available surveillance footage to be overwritten
- Not obtaining complete medical records
- Failing to document lost wages
- Assuming an insurer must accept every medical bill
- Treating a diagnosis as automatic proof of accident causation
- Ignoring relevant preexisting conditions
- Failing to explain significant treatment gaps accurately
- Assuming the first offer represents the full value of a claim
- Assuming every low offer constitutes insurance bad faith
- Confusing no-fault benefit deadlines with liability settlement deadlines
- Overlooking the 2026 motor vehicle comparative fault changes
- Assuming policy limits guarantee payment
- Claiming unsupported future medical expenses
- Overlooking potential reimbursement obligations
- Signing a release without understanding its scope
- Assuming settlement negotiations extend the lawsuit deadline
The significance of each issue depends on the particular case.
A successful injury claim requires credible evidence supporting both liability and recoverable damages.
When May Legal Guidance Be Useful?
Legal guidance may be particularly valuable when an insurer denies liability, disputes medical causation, offers substantially less than the documented losses, or raises complicated coverage questions.
Some claims require analysis of several insurance policies, multiple defendants, permanent injuries, or future medical needs.
New York’s 2026 motor vehicle reforms may also affect how insurers evaluate certain newly commenced auto injury actions.
Additional legal review may be necessary when an insurer disputes the seriousness of an injury, challenges a claimant’s percentage of fault, or requests a settlement release.
People researching personal injury attorneys may consider relevant experience with insurance negotiations, New York negligence law, and the particular accident category involved.
A legally supportable claim still depends on evidence and applicable law. Representation does not guarantee a settlement, specific payment amount, or favorable verdict.
Frequently Asked Questions About Insurance Injury Claim Evaluations
What factors do insurance companies consider when evaluating personal injury claims?
Insurance companies generally assess available coverage, legal liability, accident evidence, medical causation, documented expenses, lost earnings, and potential pain-and-suffering damages. They may also consider comparative fault and the risks of litigation. The evaluation depends on the injury, governing law, and available evidence rather than one universal settlement formula.
Why would an insurance company offer less than my medical bills?
An insurer may dispute liability, the relationship between treatment and the accident, medical necessity, or the reasonableness of expenses. Coverage limitations and comparative fault may also affect the evaluation. However, a low offer does not automatically establish that the insurer acted unlawfully. The stated reasons should be reviewed against the actual evidence.
Does New York require insurance companies to settle injury claims within 30 days?
No universal 30-day settlement deadline applies to every bodily injury liability claim. New York’s no-fault system has a separate general 30-day payment-or-denial rule after receipt of the required proof, including properly requested verification. Other claims-handling regulations establish acknowledgment and investigation requirements. These rules should not be treated as identical.
Can I negotiate a personal injury settlement if I disagree with the insurer’s offer?
Yes. A claimant may present additional medical records, liability evidence, financial documentation, or qualified expert opinions supporting a different valuation. The insurer may accept, reject, or counter the proposal. Negotiations do not guarantee settlement and generally do not suspend the deadline for filing a lawsuit.
Should future medical treatment be considered before accepting an injury settlement?
Yes. When an injury may require surgery, rehabilitation, or ongoing care, reasonably supported future treatment can affect recoverable damages. A settlement release may resolve claims covered by the agreement, including certain future consequences. The medical prognosis, applicable reimbursement obligations, and scope of the release should be understood before finalizing the settlement.
Conclusion
Insurance companies evaluate personal injury claims by examining coverage, liability, medical causation, financial losses, and the risks associated with litigation or settlement.
The process varies according to the accident. Car accident claims may involve no-fault benefits, the serious-injury threshold, and specialized comparative fault rules. Premises liability claims may depend on proof of dangerous conditions and notice. Other accident categories may involve different legal requirements.
Medical records, diagnostic findings, witness statements, photographs, surveillance footage, and financial documentation can influence how an insurer evaluates a claim. However, extensive medical treatment does not automatically establish that another party was legally responsible.
New York regulates certain insurance practices through Insurance Law § 2601 and Insurance Regulation 64. These provisions establish important claims-handling obligations but do not require insurers to accept every settlement demand or create an automatic damages action for every low offer.
The 2026 changes to New York motor vehicle law also require attention because they affect certain serious-injury and comparative fault analyses.
Settlement terms should be evaluated alongside future medical needs, insurance coverage, potential reimbursement obligations, and filing deadlines. A gross settlement and the claimant’s eventual net recovery may differ.
Understanding how insurers assess the available evidence and applicable law can help injured people make informed decisions about injury claims, settlement negotiations, and potential litigation in New York.